
Join the Crew
Get the best resources for producers delivered to your mailbox

Get the best resources for producers delivered to your mailbox

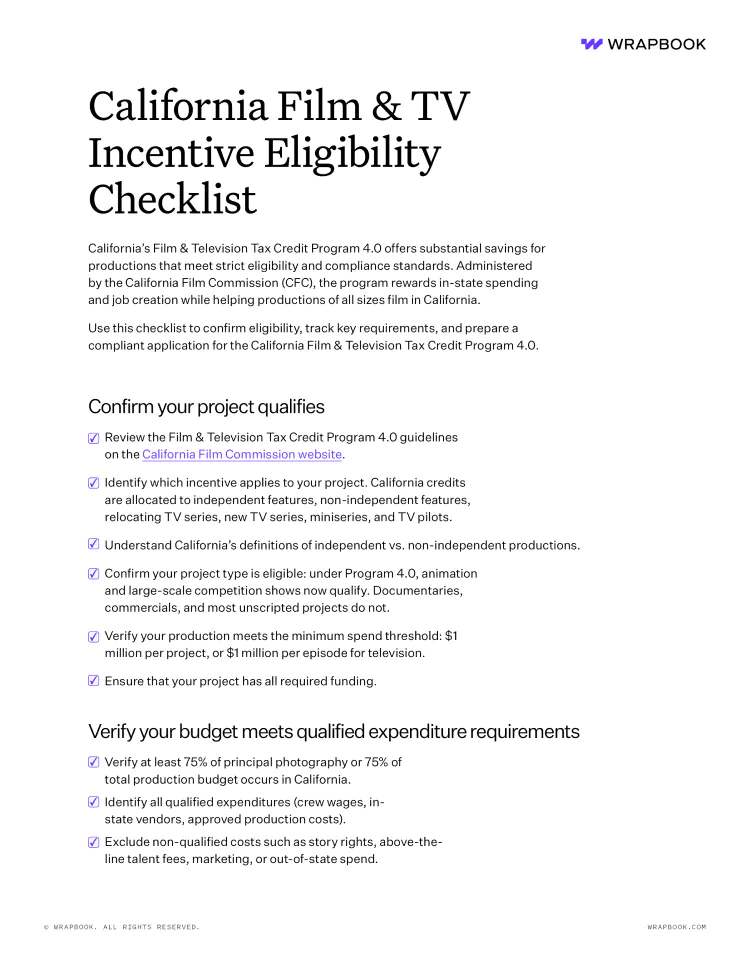
Tom is a filmmaker, producer, and marketing specialist based in Los Angeles.
At Wrapbook, we pride ourselves on providing outstanding free resources to producers and their crews, but this post is for informational purposes only as of the date above. The content on our website is not intended to provide and should not be relied on for legal, accounting, or tax advice. You should consult with your own legal, accounting, or tax advisors to determine how this general information may apply to your specific circumstances.
California just made its film incentive work better for the productions that need it most. On September 19, 2026, Governor Gavin Newsom signed AB 186 into law, exempting independent productions from the state's business tax credit cap and improving how quickly all productions can turn their credits into cash.
The change resolves a conflict that had earlier rattled the industry, when a broad corporate tax credit cap codified in July threatened to slow down the very jobs program California had just doubled in size.
In this guide, we're breaking down what AB 186 changed, how the underlying California film tax credit cap works, who benefits most, and what producers should know now.
AB 186, a budget trailer bill also referred to as SB 186, is the fix the entertainment industry had been pushing for since June. It doesn't undo the state's business tax credit cap entirely, but it takes the pressure off the productions most exposed to it and sweetens the terms for everyone else.
Here is what the law actually does.
Independent productions typically run smaller budgets, claim smaller tax credits, and rely most heavily on monetizing those credits, so a firm annual ceiling hit them hardest. AB 186 restores their clean, predictable access to California film tax credits.
Independent productions often monetize credits by selling them to financiers, and this provision protects that mechanism from the annual limit going forward.
Productions that elect to receive a cash refund on unused credits can now receive 95% of the credit value, up from 90%, and the state must pay out that refund within two years instead of five. Compressing the payout window from five years to two is a meaningful improvement in time-to-cash for any production waiting on a large refund.
Lastly, Motion Picture Credit 2.0 and 3.0 credits can now be carried forward for up to 15 years, giving productions still holding credits from earlier program versions far more time to realize their full value. To carry forward in years 10 through 15, a production or related company must be an "active participant" in the current program.
The industry's original ask was a full, industry-wide exemption. AB 186 stops short of that, as major studio productions remain subject to the claim cap.
But for independent productions, and for anyone weighing a cash-out on their credits, this is a clear step forward. As Shane Gusman, lobbyist for SAG-AFTRA and the Teamsters in California, told CalMatters, lawmakers delivered "enough so that the program will continue to work."
To understand why AB 186 matters, it helps to know what it's responding to.
SB 122 is a California budget trailer bill, signed into law on June 29, 2026 as part of the 2026-27 state budget package. It was a broad revenue measure, passed to raise money by limiting corporate tax breaks across every sector, and it made several changes to how business tax credits work in the state.
Most notably, SB 122:
In a nutshell, the SB 122 cap is a statewide limit on how much in business tax credits any single taxpayer can apply against their California income or franchise tax liability in a given year.
It does not cap how many credits a taxpayer can earn; it caps how many can be used in a single tax year to reduce a corporate taxpayer's California tax liability. Under the cap, a company that earns $8 million in California film tax credits can only apply $5 million of it in year one, with the rest carried forward.
The catch was that SB 122 wasn't written with the film industry in mind. CA film tax credits got swept in alongside every other business credit under the California Revenue and Taxation Code. A cap designed as a general revenue measure landed squarely on a jobs program California had just expanded, which is exactly the tension AB 186 was written to relieve.
The Film & Television Tax Credit Program 4.0, expanded by AB 1138 and administered by the California Film Commission, allocates $750 million annually in credits based on qualified California expenditures. Most productions receive a base credit of 35% of qualified in-state spending, with 40% for first-season relocating television series and additional uplifts for out-of-zone filming, VFX work, and certain labor categories.
The cap never touched how credits are earned. A production still applies through the Commission, still earns credits based on its qualified California expenditures, and still receives a Tax Credit Certificate upon completion. What the cap changed was how quickly that certificate could be monetized.
Before AB 186, that created what industry observers called a "double cap" problem. Program 4.0 is already competitively allocated, with a $750 million annual ceiling and per-project limits. SB 122 added a second ceiling at the point of monetization.
AB 186 removes that second ceiling for independent productions and softens it for everyone else through the longer carry-forward and faster, larger refunds. The monetization cap now applies primarily to non-independent studio productions, and even for them, the runway to full value is shorter than it was in July.
The result of AB 186 is a much friendlier landscape for most productions filming in California, with one group still working around the cap.
They are fully exempt from the annual cap and can once again use, carry, and sell their California film tax credits without hitting the $5 million ceiling.
The move to a 95% refund paid within two years applies across Program 4.0, so any production electing a refund gets more money, sooner.
A studio feature or returning series generating credits well above $5 million still operates under the cap and still faces a multi-year path to full monetization. AB 186 improves the terms of that timeline through the 15-year carry-forward and faster refunds, but it does not exempt studios outright.
The per-taxpayer cap applies regardless of how many productions generated their credits, so a longer carry-forward window is especially valuable to companies juggling several at once.
The industry got here through a fast, unusually unified campaign.
A group of roughly 40 California legislators sent letters to Governor Newsom and legislative leaders arguing that the cap undercut recent efforts to expand Program 4.0 and bring production back to California. Assemblymember Rick Chavez Zbur, who co-authored last year's expansion, and CAA CEO Bryan Lourd, who urged lawmakers to act, were among the most visible voices.
Studios, the Motion Picture Association, the Entertainment Union Coalition, the Producers Guild of America, and unions including SAG-AFTRA all lined up behind a fix. Lawmakers ultimately chose a targeted exemption for independent productions rather than an industry-wide carve-out, out of concern that exempting the entire film industry would invite other sectors to seek the same treatment and unwind the revenue purpose of SB 122.
The outcome is a partial exemption that restores the program's core function for independents and improves it for everyone. Zbur described AB 186 as legislation that will "provide greater stability and certainty for productions and workers." For a program California had just bet $750 million a year on, that stability is the point.
The right next step depends on which side of the exemption you fall on.
Work with your production accountant or tax counsel to verify that your project qualifies as independent under AB 186 and understand how the exemption applies to your plans to use or sell credits, particularly how "sold credits" are treated for tax years beginning January 1, 2027.
Faster, larger refunds change the effective time-to-cash on California credits. Lenders and gap financiers who treat tax credits as collateral or recoupment should understand which productions are now exempt and how the improved refund terms shorten the wait.
The CFC is the authoritative source on how AB 186 is being applied to credits under Program 4.0 and is best positioned to confirm the mechanics as the changes take effect in 2027.
For producers navigating a fast-moving incentive environment in California and across the country, Wrapbook's Production Incentive Center is an essential resource.
The Production Incentive Center is a comprehensive resource designed to help producers research, compare, and navigate film incentive programs across the United States and its territories.
With the State Incentive Map, you can quickly survey programs nationwide. The Incentive Comparison Tool lets you size up how California's program stacks up against competitive programs in states like Georgia, New York, New Mexico, and Nevada.
With California's incentive now more accessible than it was a few months ago, the Production Incentive Center is the right place to start when evaluating your options.
Whether you're in pre-production on an independent feature, mid-stream on a studio series, or planning future California shoots, AB 186 is good news. Independent productions can fully utilize California film tax credits again, and refundable elections pay more, faster.
To stay current on California film tax incentives and track developments across every state program, visit Wrapbook's Production Incentive Center. For a broader look at how state film incentives work and how producers use them, our comprehensive guide to production incentives is a great next read.


